


SDLA Compliance Resource
Complete Calendar-Year-End W-2, 1099, and ACA Reporting
An implementation guide for preparing and filing 2026 Forms W-2, 1099, and 1095-C, including year-end taxable-benefit adjustments.
In Plain Language: After December's last payroll, the LEA must finalize each employee's wages and taxable benefits (such as group-term life over $50,000 or personal use of district vehicles), issue W-2s, and file them with the Social Security Administration. It must also issue 1099s to independent contractors and, as an applicable large employer, 1095-C health-coverage statements.
Why this matters
Late or wrong forms create penalties and employee frustration. Corrections after filing (W-2c) are time-consuming, so the adjustments must be in before December's final payroll closes.
Joint ownership
District: payroll, HR/benefits, and accounts payable (1099 vendors). County office: often runs W-2 processing and sets cut-off dates. Employees and vendors: receive forms.
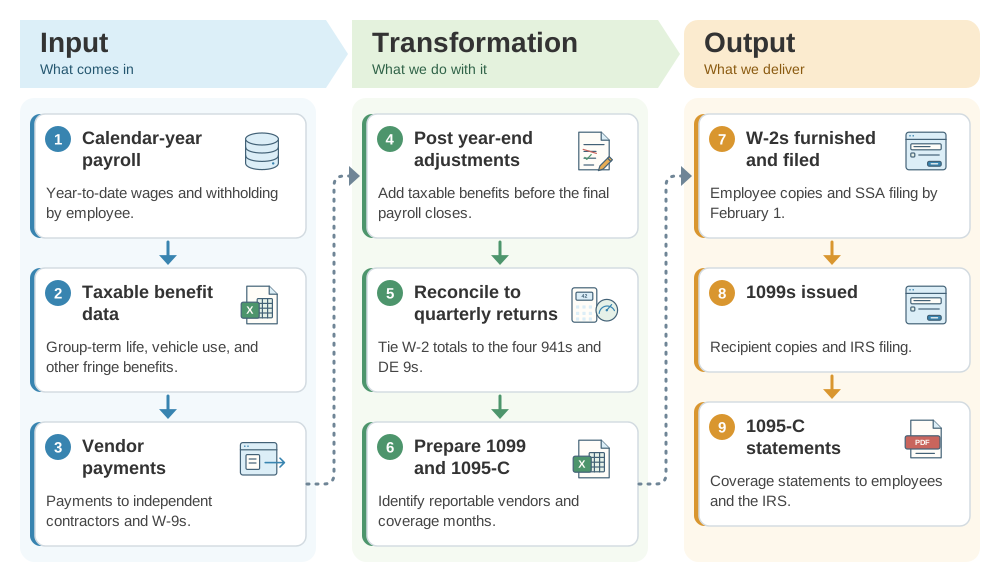
From calendar-year payroll to filed W-2, 1099, and 1095-C forms: the SDLA ITO workflow
This workflow finalizes a calendar year of wages and payments into federal information returns. This SDLA ITO (Input, Transformation, Output) graphic shows how the inputs become the outputs in 9 steps.
Implementation workflow
- NovemberCollect adjustments.Gather taxable benefits and update vendor W-9s.
- Early DecemberMeet county cut-offs.Post adjustments before the county's year-end deadline.
- JanuaryReconcile and prepare.Tie totals to quarterly returns; prepare all forms.
- By February 1Furnish and file.W-2s to employees and SSA; 1099-NEC to recipients and IRS.
- MarchACA and remaining filings.Furnish 1095-C and complete electronic IRS filings.
Year-end reporting checklist
- Taxable benefits posted before final payroll.
- W-2 totals reconcile to quarterly returns.
- 1099 vendors identified with valid W-9s.
- Forms furnished and filed by the deadlines.
- Process documented for corrections (W-2c).
Official guidance and help
- SSA Employer W-2 FilingW-2 electronic filing.
- IRS Form 1099-NECNonemployee compensation reporting.
- IRS Affordable Care Act Information ReturnsForms 1094-C and 1095-C.
Source review completed October 25, 2026. Verify your county office's year-end payroll cut-offs and the current IRS deadlines before December.