


SDLA Compliance Resource
Determine and Post Education Protection Account Spending
An implementation guide for deciding how Education Protection Account funds will be spent in open session, posting the annual accounting on the website, and supporting the audit.
In Plain Language: Part of each LEA's LCFF funding comes from the Education Protection Account created by Propositions 30 and 55. The constitution requires the board to decide how those funds are spent in a public meeting, to post an annual accounting of EPA receipts and spending on the website, and not to spend them on administrative salaries or other administrative costs. The annual audit verifies compliance.
Why this matters
EPA compliance is tested in every annual audit. A missing resolution, missing website posting, or administrative charges are audit findings that the board must then correct publicly.
Joint ownership
District: chief business official prepares the spending plan and accounting; the board adopts it; the web team posts it. Auditor: verifies compliance.
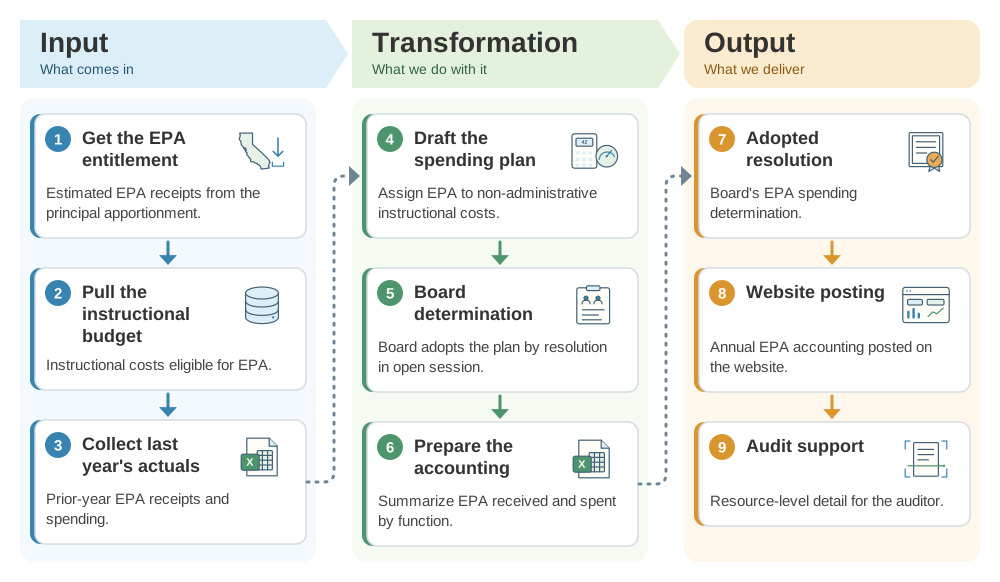
From EPA entitlement to a public spending accounting: the SDLA ITO workflow
This workflow documents the board's EPA decision and the public accounting the constitution requires. This SDLA ITO (Input, Transformation, Output) graphic shows how the inputs become the outputs in 9 steps.
Implementation workflow
- Budget developmentPlan.Estimate EPA receipts and assign them to eligible costs.
- Budget adoptionBoard determination.Adopt the EPA spending plan in open session.
- After year-end closePrepare the accounting.Summarize actual EPA receipts and spending.
- AnnuallyPost.Publish the accounting on the website.
- AuditSupport the audit.Provide resource detail and the posting to the auditor.
EPA checklist
- Spending decision made in open session.
- No administrative costs charged to EPA.
- Annual accounting posted on the website.
- EPA tracked in its designated SACS resource.
- Audit documentation retained.
Official guidance and help
- CDE Education Protection AccountEPA guidance and allocations.
- California Constitution, Article XIII, Section 36Source of the EPA requirements.
Source review completed October 25, 2026. Verify the current audit guide's EPA procedures before year-end.