


SDLA Compliance Resource
File Charter Nonprofit Annual Returns (IRS 990, FTB 199, and Registry Filings)
An implementation guide for nonprofit public benefit corporations operating charter schools to file the IRS Form 990, California Form 199, and any Attorney General Registry renewal for the June 30 fiscal year.
In Plain Language: A charter school run by a nonprofit corporation must file the corporation's annual returns: IRS Form 990, California Form 199 (or the 199N e-Postcard for small organizations), and the Attorney General's Registry of Charities renewal unless an exemption applies. For a June 30 year end, these are due in mid-November. Many authorizers also require a copy.
Why this matters
Late or missing returns can bring penalties, suspension of the corporation's status, or loss of tax exemption, and authorizers treat them as indicators of governance health.
Joint ownership
Charter: chief business officer, back-office provider, and tax preparer; the board reviews the 990 before filing. Authorizer: may collect copies.
From the audited year to filed nonprofit returns: the SDLA ITO workflow
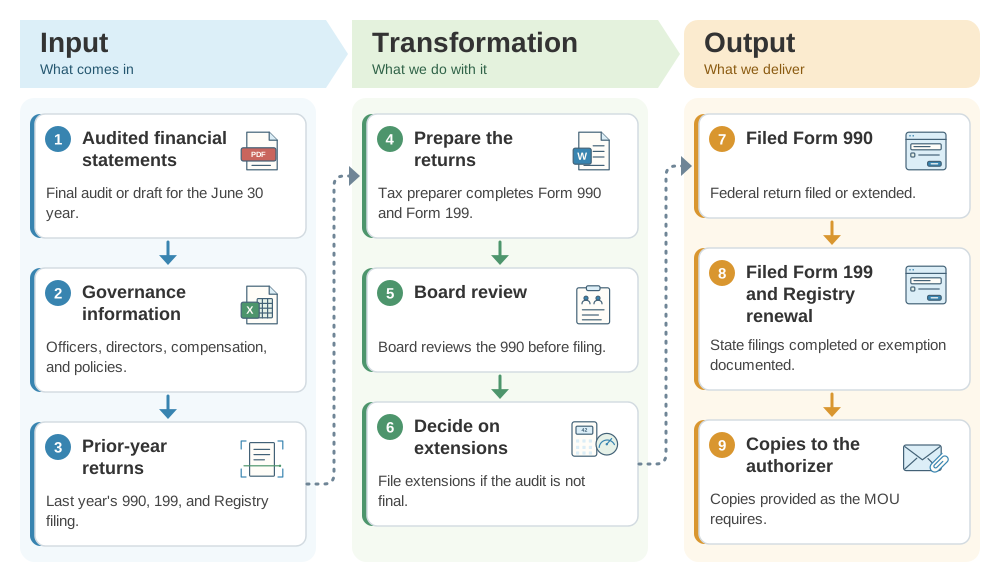
This workflow coordinates the audit, the tax preparer, and the board for the charter corporation's annual filings. This SDLA ITO (Input, Transformation, Output) graphic shows how the inputs become the outputs in 9 steps.
Implementation workflow
- August–SeptemberGather information.Collect governance and financial data for the preparer.
- OctoberPrepare and review.Draft returns; schedule the board review.
- Early NovemberBoard review.Board reviews the 990 at a public meeting.
- By November 16File or extend.File the returns or extensions and save confirmations.
- After filingShare.Send copies to the authorizer if required.
Charter nonprofit filing checklist
- Fiscal year end and due dates confirmed.
- Board review documented before filing.
- Registry renewal filed or exemption confirmed.
- Extensions filed if needed.
- Authorizer copies provided.
Official guidance and help
- IRS Form 990Return of organization exempt from income tax.
- Attorney General Registry RenewalsRRF-1 renewal requirements and exemptions.
- FTB Publication 1068: Exempt Organizations Filing RequirementsForm 199 and 199N requirements.
Source review completed October 25, 2026. Verify your corporation's fiscal year, any exemption from the Registry, and extension status with your tax preparer.