


SDLA Compliance Resource
Review Certification of the Second Principal Apportionment
The CDE certification that converts P‑2 and related data into the final current-year state-aid payment calculation and the baseline for annual closeout.
In Plain Language: Retrieve CDE’s certified P‑2 exhibits, reconcile inputs and calculated funding to the submitted PADC/CALPADS/local-revenue package, assess the June payment and year-end accrual, and identify items that belong in Annual reporting or an authorized correction path.
Why this matters
P‑2 drives the final state-aid payment for the fiscal year. An unexplained variance can distort year-end receivables, cash, reserves, program allocations, and the starting point for Annual data.
Primary ownership
Primary owner: chief business official/principal-apportionment fiscal lead. Partners: PADC, attendance, budget/accounting, CALPADS, charter/COE, SELPA, local revenue, cash management, auditor, and superintendent/designee.
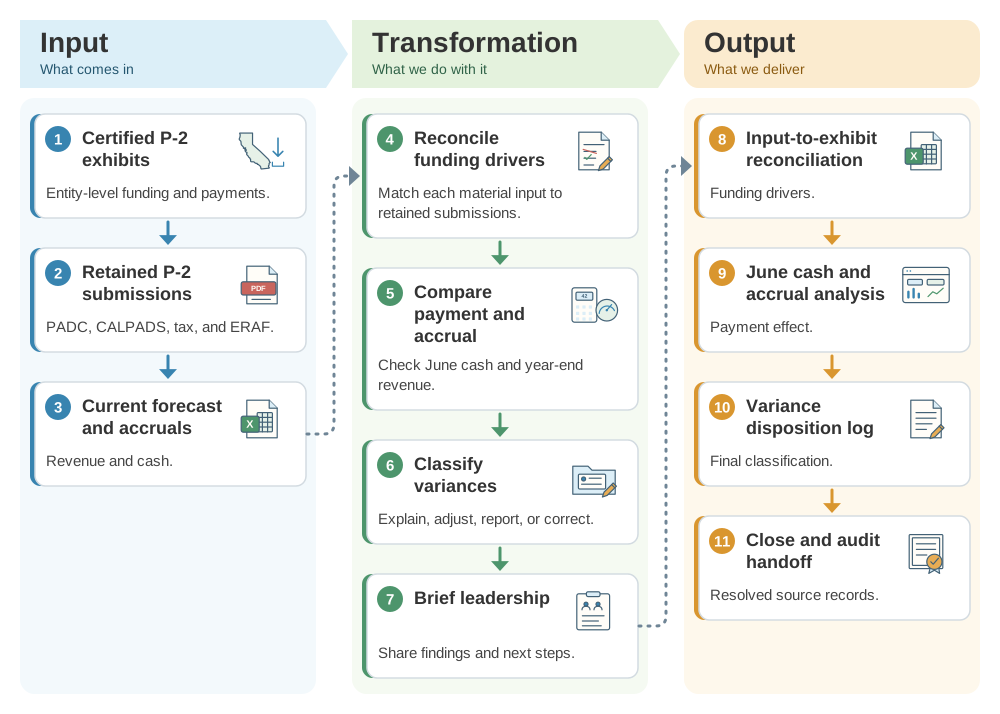
From certified P-2 exhibits to a year-end close handoff: the SDLA ITO workflow
The certified calculation sets the final current-year payment, so inputs, cash, and accruals must be reconciled. This SDLA ITO (Input, Transformation, Output) graphic shows how the certified P-2 exhibits, entity payment details, and retained P-2 submissions become the input reconciliation, the variance disposition log, and the close and audit handoff.
Operational workflow
- Download certified P‑2 exhibits and entity-level funding/payment details.
- Reconcile every material funding driver to retained P‑2, CALPADS, tax, ERAF, and partner submissions.
- Compare the June payment, year-end revenue/accrual, and program allocations with the current forecast.
- Document and assign variances to explanation, accounting adjustment, Annual reporting, or authorized correction.
- Brief leadership and hand off resolved source records to year-end close and audit.
Implementation pathway
Evidence to retain
- Certified P‑2 exhibits and detail
- Input-to-exhibit reconciliation
- June cash and year-end accrual analysis
- Variance disposition log
- Leadership review and audit handoff
Official guidance and help
- CDE PA DeadlinesOfficial P‑2 certification date
- CDE FY 2026–27 Principal ApportionmentCertified exhibits
- CDE Payment ScheduleJune payment context
- CDE PADC Due DatesAnnual follow-on screens
Source review completed August 30, 2026. Verify current CDE, PADC, ASSIST, entity-specific, grant, fiscal, attendance, and partner instructions before acting.