


SDLA Compliance Resource
Adopt Budget Transfer and Temporary Interfund Borrowing Resolutions
An implementation guide for authorizing budget transfers, year-end appropriation transfers, and temporary interfund cash borrowing, and documenting repayment within the statutory limits.
In Plain Language: The board controls the budget. Moving appropriations between major categories, making year-end transfers, or temporarily lending cash from one fund to another all require board authority, usually by resolution. Temporary interfund loans under EC 42603 are not income to the borrowing fund, are capped at 75 percent of the lending fund's maximum balance, and must be repaid on time.
Why this matters
Unauthorized transfers and unrepaid interfund loans are recurring audit findings and county-review concerns. Borrowing restricted or bond funds carries extra legal risk, and a fund that cannot repay a loan signals a cash problem the interim certification must reflect.
Joint ownership
District: chief business official and accounting prepare resolutions and track loans; the board adopts them. County office: processes transfers, may require copies of resolutions, and reviews cash in interim reports. Auditor: tests authorization and repayment.
Transfer and borrowing actions
| Action | Typical authority | Key control |
|---|---|---|
| Budget transfers between major object classifications | Board resolution or ratification (EC 42600 et seq.) | Board approval before or ratification promptly after posting. |
| Year-end appropriation transfers | Board resolution authorizing year-end adjustments | Completed before the county's prior-year close date. |
| Temporary interfund borrowing | Board resolution (EC 42603) | No more than 75% of the lending fund's maximum balance; repayment deadline tracked. |
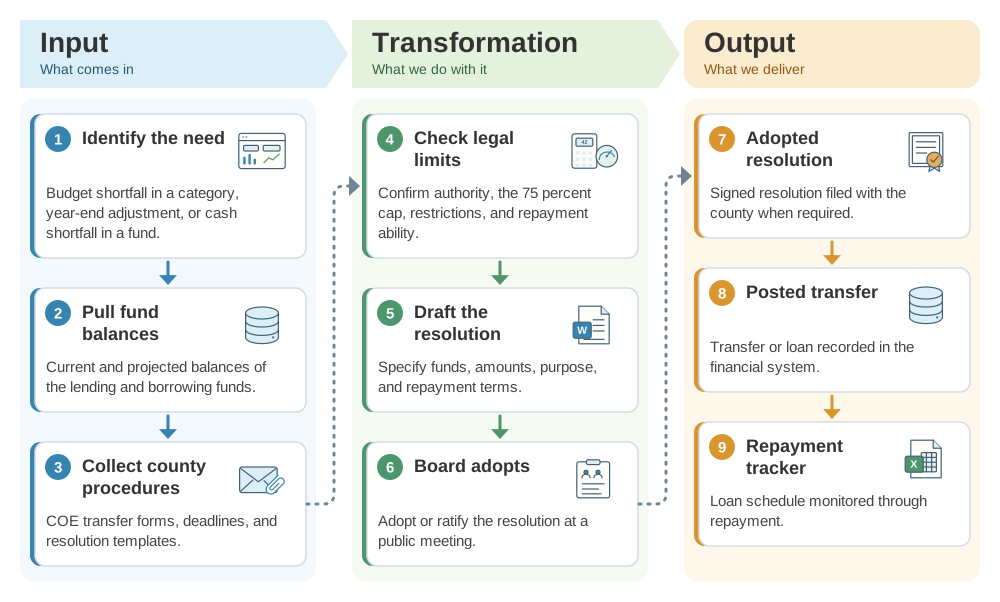
From a budget or cash need to an authorized, documented transfer: the SDLA ITO workflow
This workflow keeps every transfer and interfund loan authorized, recorded, and repaid. This SDLA ITO (Input, Transformation, Output) graphic shows how the inputs become the outputs in 9 steps.
Implementation workflow
- Budget adoption or JuneAdopt annual authorizations.Adopt resolutions authorizing budget transfers and any planned interfund borrowing.
- During the yearProcess and ratify.Post transfers and bring them to the board for approval or ratification.
- MonthlyMonitor loans.Track outstanding interfund loans against cash projections.
- Before year-end closeYear-end transfers.Complete year-end appropriation transfers before the county close date.
- Statutory deadlineRepay.Repay interfund loans by June 30, or in the next year if made in the final 120 days.
Transfer and borrowing checklist
- Annual authorizing resolutions adopted and on file.
- Each interfund loan documented with amount, purpose, and repayment date.
- 75 percent cap verified against the lending fund's maximum balance.
- Bond counsel consulted before borrowing bond proceeds.
- Outstanding loans disclosed in interim reports and cash projections.
Official guidance and help
- Education Code 42603Temporary interfund transfers and repayment rules.
- FCMAT Fiscal Alert: Interfund BorrowingRisks of borrowing bond proceeds.
Source review completed October 25, 2026. Verify your county office's transfer procedures and resolution templates before adoption.