


SDLA Compliance Resource
Submit Eligible Audit Adjustments and Prior-Year Corrections
A controlled March correction deadline requiring the right fiscal year, reporting period, mode, materiality rule, audit authority, and CDE access.
In Plain Language: Inventory each proposed correction by year, period, screen, amount, funding effect, and authority; obtain the required audit finding or auditor concurrence; request access when needed; enter it in the correct system/mode; and verify the accepted result.
Why this matters
A valid underlying issue can still fail if filed in the wrong year, period, mode, or system—or without required audit support. Older-year claims and ADA changes have special eligibility/materiality limits.
Primary ownership
Primary owner: principal-apportionment/PADC lead. Partners: auditor, CALPADS, attendance, fiscal, COE/charter oversight, superintendent/designee, legal counsel when needed, and CDE PASE/PADC staff.
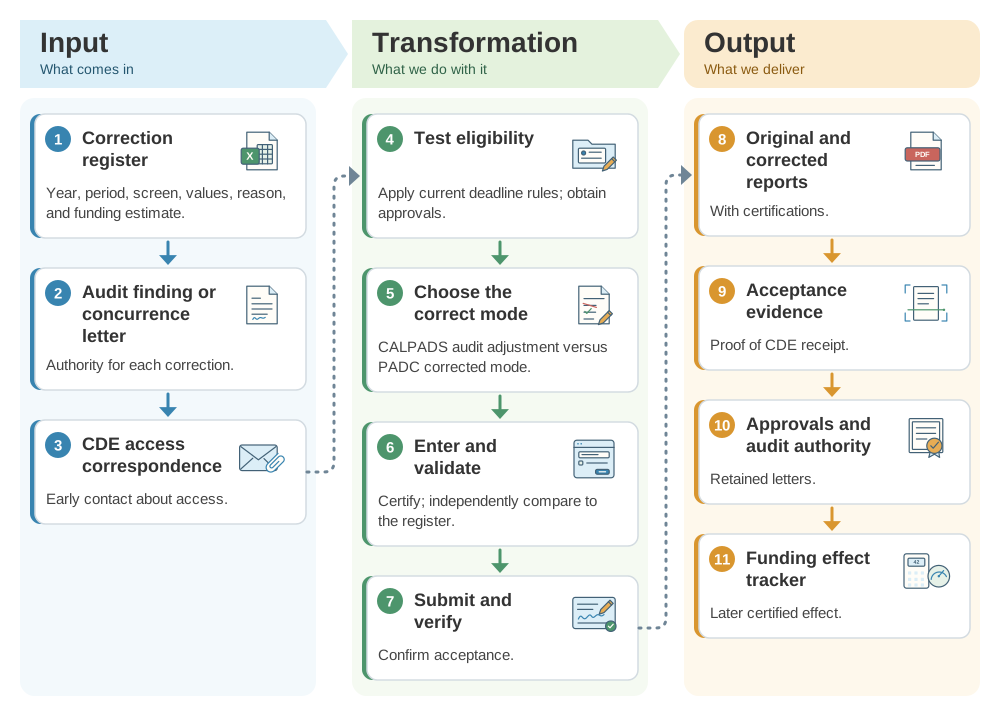
From a correction register to accepted audit adjustments: the SDLA ITO workflow
Each correction needs the right year, period, mode, audit authority, and CDE access. This SDLA ITO (Input, Transformation, Output) graphic shows how the correction register, audit findings or letters, and CDE access correspondence become the original and corrected reports, the acceptance evidence, and the funding reconciliation.
Operational workflow
- Create a correction register with entity, fiscal year, period, screen/data element, original value, proposed value, reason, and estimated impact.
- Test eligibility against the current deadline rules and obtain audit findings/letters and internal approvals.
- Contact CDE early for access and choose CALPADS audit-adjustment versus PADC corrected mode correctly.
- Enter, validate, certify, and independently compare the corrected report with the approved register.
- Retain acceptance evidence and track the eventual certified funding effect.
Implementation pathway
Evidence to retain
- Correction register and funding estimate
- Audit finding or concurrence letter
- CDE access correspondence
- Original/corrected reports and certifications
- Acceptance and later funding reconciliation
Official guidance and help
- CDE PA DeadlinesMarch correction rules and auditor-letter elements
- CDE PADCWeb application and correction resources
- CDE CALPADSAudit-adjustment context
- CDE Audit ResolutionAudit support resources
Source review completed August 30, 2026. Verify current CDE, PADC, ASSIST, entity-specific, grant, fiscal, attendance, and partner instructions before acting.