


SDLA Compliance Resource
Approve and File 2025–26 Unaudited Actuals
An implementation guide for closing the prior year, reconciling SACS data, obtaining board approval, and filing the unaudited actual financial report with the county office by September 15.
In Plain Language: By September 15 each year, the governing board must approve the prior year's actual revenues, expenditures, and ending balances and file them with the county office in the state's SACS format. The county reviews the filing and forwards it to CDE by October 15. The numbers become the starting point for the audit, the next interim reports, and the Gann limit.
Why this matters
Unaudited actuals reset the beginning balance used in the first interim report and multiyear projection. A late or unreconciled filing delays county review, undermines the auditor's starting point, and can carry errors into apportionment and the Gann calculation. CDE publishes the data in the SACS Data Viewer, so errors become public.
Joint ownership
District: chief business official, accounting/fiscal services, payroll, categorical program managers, and the board. Auditor: uses the filing as the starting trial balance. County office: reviews the filing, the technical review checks, and the certification, then transmits to CDE.
What the filing must contain
| Component | What to verify |
|---|---|
| SACS unaudited actual data (all funds) | Balances tie to the general ledger; restricted ending balances match resource-level carryover. |
| Technical review checks | No fatal exceptions; warnings explained in the transmittal. |
| Gann limit data | Prior-year and current-year appropriations-limit worksheets submitted with the SACS file (GC 7906(f)). |
| Board approval and certification | Board action at a public meeting before the September 15 filing. |
| Supplemental forms required by the county | Any county-specific forms, schedules, or narratives listed in the COE's year-end instructions. |
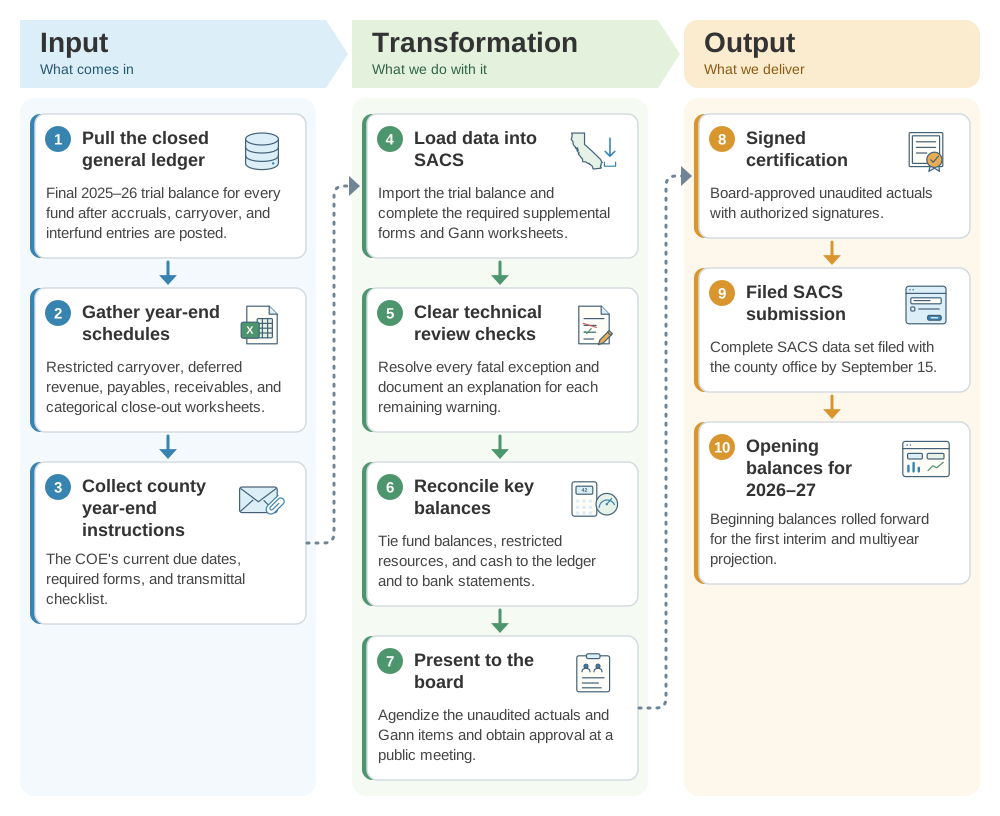
From a closed general ledger to a filed unaudited actuals report: the SDLA ITO workflow
Unaudited actuals turn a closed prior year into the official starting balance for the new year. This SDLA ITO (Input, Transformation, Output) graphic shows how the inputs become the outputs in 10 steps.
Implementation workflow
- JulyClose the prior year.Post accruals, carryover, deferred revenue, and interfund entries; lock the prior-year period after the county's close date.
- Early AugustLoad and validate SACS.Import data, complete supplemental forms, and run the technical review checks.
- Mid-AugustReconcile and document.Tie fund and restricted balances, explain warnings, and prepare the board narrative.
- Before September 15Board approval.Agendize the unaudited actuals with the Gann resolution and obtain approval at a public meeting.
- By September 15File with the county.Submit the SACS data and required certifications to the COE; charters also file with the chartering authority.
- By October 15Respond to county review.Answer county questions promptly so the COE can transmit the data to CDE.
Unaudited actuals readiness checklist
- Prior-year period closed and no late postings pending.
- Restricted ending balances reconciled to resource-level carryover schedules.
- SACS technical review checks run with zero fatal exceptions.
- Gann worksheets completed and the resolution scheduled for the same or an earlier meeting.
- Board agenda, minutes, and signed certification retained with the filing.
- Beginning balances rolled into the 2026–27 budget for first interim.
Official guidance and help
- 2026 Financial Reporting Calendar — DistrictStatutory due dates and citations for budget, interim, unaudited actuals, and audit filings.
- SACS Financial Reporting SoftwareSoftware, technical review checks, and user guides.
- Education Code 42100Statutory requirement to approve and file the prior-year statement.
Source review completed October 25, 2026. Verify your county office's internal due date, which may be earlier than September 15, and any county-specific forms before filing.